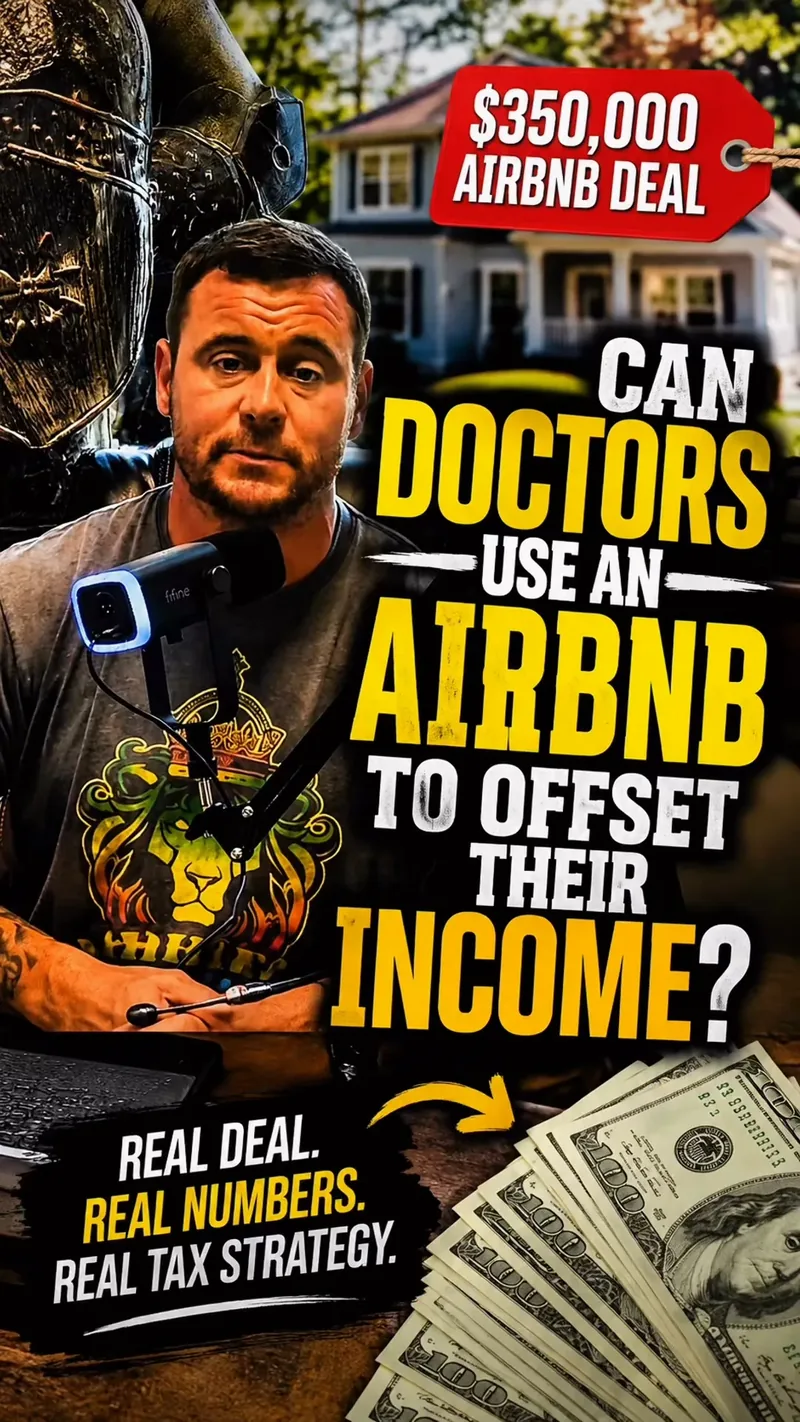
Most high-income earners understand that real estate offers significant tax advantages. The problem is that if you're not a real estate professional, losses generated by a traditional rental property are generally considered passive losses — meaning they typically can't be used to offset W-2 wages or other active income.
Short-term rentals can be different.
I'm currently working on an actual short-term rental investment in Louisville that provides a good example of how this strategy can work.
A Real-World Example
The property is an existing short-term rental with a $350,000 purchase price. Over the trailing 12 months, it generated approximately $64,900 in gross booking revenue and nearly $31,900 in net operating income before debt service.
With 20% down, estimated closing costs and a cost-segregation study, we're projecting approximately $85,500 in total cash required to acquire the property.
But the tax treatment is where things get particularly interesting.
The 7-Day Rule
Under the passive-activity rules, if the average period of customer use is seven days or less, the activity generally isn't classified as a "rental activity" for purposes of Section 469.
That doesn't automatically make the losses nonpassive. The owner must still materially participate in operating the property.
One potential material-participation test requires the owner to participate for more than 100 hours during the year while participating at least as much as any other individual.
That can include legitimate operational activities such as managing pricing and availability, handling guest issues, coordinating repairs, managing vendors, inspecting the property and making other day-to-day operating decisions. A spouse's participation can also count toward the taxpayer's participation.
Interestingly, the property we're evaluating doesn't currently meet our target. Based on its existing booking history, we estimate an average stay of approximately 8.4 nights. Part of the strategy would therefore involve changing the booking mix to bring the average stay to seven days or less.
Watch the full breakdown: I walk through this exact deal, numbers and all, in this week's video. Watch on Facebook →
Where Cost Segregation Comes In
Once the passive-activity requirements are satisfied, cost segregation can potentially accelerate a substantial amount of depreciation into the first year of ownership.
For this particular $350,000 property, our preliminary cost-segregation analysis estimates approximately $28,400 in first-year federal tax savings at the marginal tax rate used in our model.
Combine that potential tax benefit with approximately $10,600 in projected annual cash flow after debt service, and the model produces nearly $39,000 of combined first-year cash flow and estimated federal tax savings against approximately $85,500 initially invested.
And, of course, the investors still own the underlying real estate.
This Isn't an Automatic Airbnb Write-Off
There are several important requirements and limitations.
- The average-stay requirement must actually be satisfied.
- The owners must legitimately materially participate and should document their participation.
- Basis, at-risk rules, depreciation rules, personal use and other tax limitations can also affect the ultimate deduction.
That's why this isn't simply a strategy of "buy an Airbnb and write it off."
But for physicians, business owners and other high-income professionals who have been told that real estate losses can't help them because they aren't real estate professionals, short-term rentals can create an entirely different conversation.
Sometimes changing the type of rental property you own — and how you operate it — can dramatically change the tax treatment.
This article is for educational and discussion purposes only and is not tax, legal or financial advice. Tax treatment depends on each taxpayer's individual circumstances. Consult a qualified CPA or tax professional before relying on this or any other tax strategy.
Have a question about your own situation?
Every episode and post starts from a real client question. If yours isn't covered yet, let's talk it through directly.
Book a Strategy Call